
For many Americans, a 401(k) is one of their largest financial assets. So, when someone begins thinking about buying a home—especially coming up with a down payment—it isn’t surprising that retirement savings may enter the conversation.
A recent graphic we reviewed from Keeping Current Matters (KCM) looks at median 401(k) balances by age and raises the question:
Should retirement savings ever be considered when buying a home?
Before discussing the graph, an important clarification:
Alpha II Realty does not provide investment, financial, tax, or retirement advice. We’re sharing this information for general educational purposes and encourage anyone considering using retirement assets to speak with their financial advisor, CPA, retirement-plan administrator, or another qualified professional.
What Does the Chart Show?
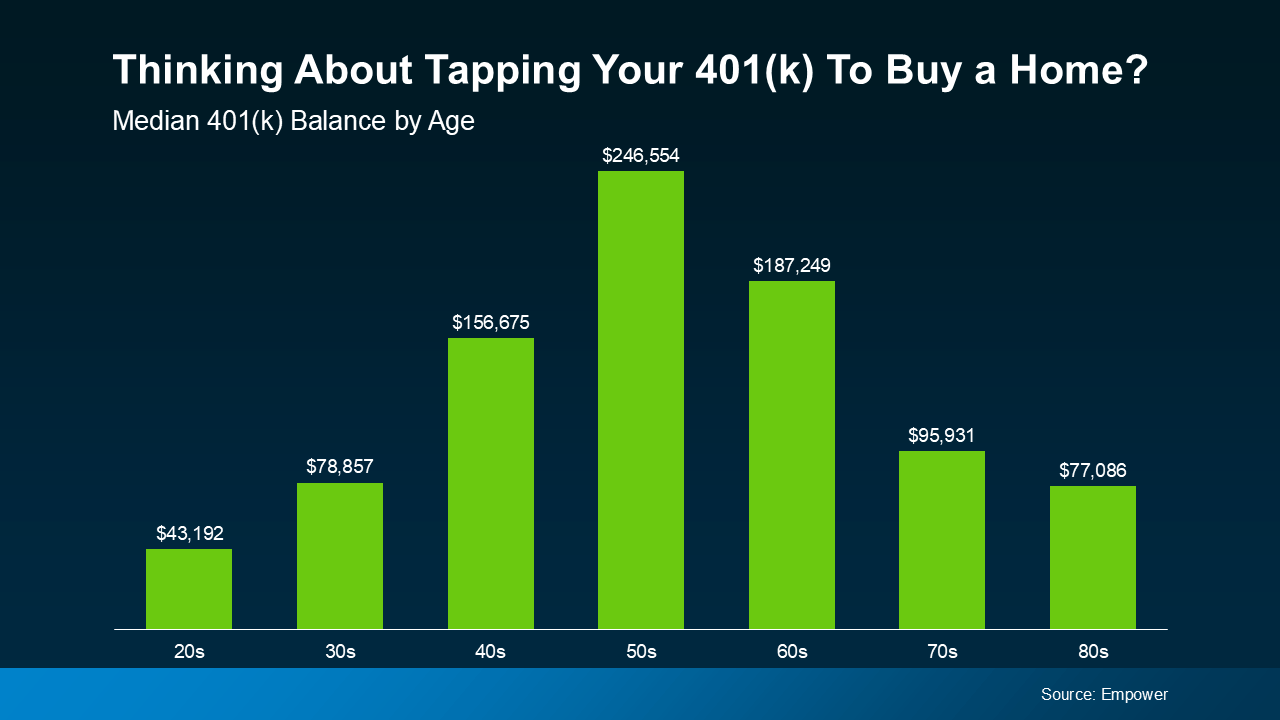
According to the Keeping Current Matters graphic, which identifies Empower as the underlying data source, median 401(k) balances vary considerably by age:
- 20s — $43,192
- 30s — $78,857
- 40s — $156,675
- 50s — $246,554
- 60s — $187,249
- 70s — $95,931
- 80s — $77,086
The chart isn’t telling someone that they should use this money to purchase a home. Instead, it highlights that many Americans have accumulated meaningful assets inside employer-sponsored retirement accounts.
Buying a Home Is a Financial Decision
A home purchase involves much more than finding a property you like.
Buyers need to consider the down payment, mortgage payment, closing costs, property taxes, insurance, HOA fees when applicable, maintenance, and their overall financial situation.
And if someone is considering accessing a 401(k), there can be additional questions involving plan rules, taxes, penalties, loans, withdrawals, and the long-term effect on retirement savings.
Those questions are outside the role of a Realtor and should be discussed with the appropriate financial and tax professionals.
Our Role Is the Real Estate Side
At Alpha II Realty, our job isn’t to tell you where the money for your home purchase should come from.
Our role is to help you understand the real estate side of the decision.
If you’re Looking for a Home in Las Vegas, we can help research properties within your price range, review comparable sales, explore different neighborhoods, evaluate current inventory, and help you understand what’s happening in the local market.
We also work with Las Vegas-area lenders who can explain mortgage programs, qualification requirements, down-payment options, and financing alternatives that may be available.
From there, you and your financial professionals can determine what makes sense for your individual situation.
Start With Information
The most important takeaway from this Keeping Current Matters graphic isn’t that retirement money should—or shouldn’t—be used to purchase real estate.
It’s that buying a home often involves coordinating several pieces of your financial life.
Before making a major decision involving retirement savings, understand your options and consult the appropriate professionals.
And when you’re ready to understand the housing side of the equation, Alpha II Realty can help.
Looking for a Home in Las Vegas?
Alpha II Realty has been serving the Las Vegas Valley since 1981.
Whether you’re beginning to explore homeownership, trying to determine what homes are available within your budget, or ready to start looking at properties, we’ll help you research the Local Las Vegas Real Estate Market.
Contact Cristine Bullard, Broker, with Alpha II Realty to discuss your Las Vegas real estate needs.
Graphic reviewed through Keeping Current Matters. Data source identified on the graphic: Empower. Alpha II Realty does not provide investment, financial, tax, or retirement advice. Consult qualified professionals before making decisions involving retirement assets.